Zimbabwe’s housing sector has significant potential for growth, with improved access to affordable financing emerging as a key factor in accelerating property development and expanding homeownership opportunities.
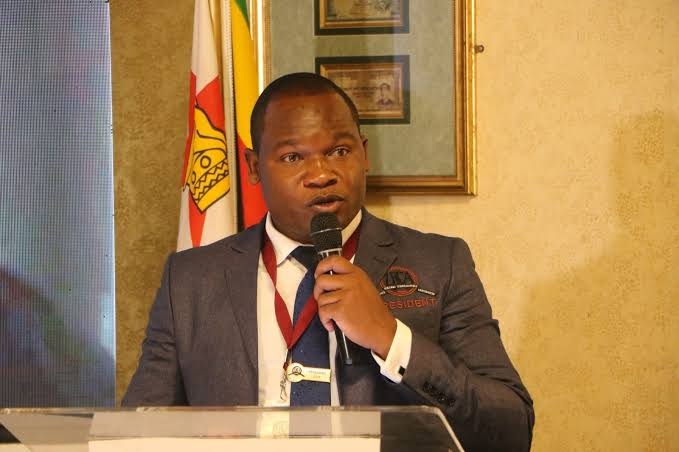
Speaking on the sidelines of the Zimbabwe Real Estate and Construction Summit, in Harare, yesterday, the president of the Zimbabwe Building Contractors Association, Dr Tinashe Manzungu, said the establishment of a dedicated mortgage financing institution could be the answer to home seekers.
“The biggest challenge is access to capital. A dedicated mortgage financing institution could provide a sustainable funding framework for developers while enabling more Zimbabweans to access long-term loans to purchase homes,” Manzungu said.
He said developers were increasingly relying on instalment-based payment arrangements, under which buyers paid for properties over periods of five to 10 years, sometimes contributing as little as US$50 or US$100 monthly.
While such arrangements have provided an alternative route to homeownership, Manzungu said they tied up developers’ capital for extended periods, limiting their ability to reinvest in new housing projects and increase supply.
For prospective homeowners, particularly young people, accessible mortgage facilities would create more flexible opportunities to acquire completed properties through manageable long-term repayments.
Manzungu said Zimbabwe could unlock greater investment in the housing sector by establishing a dedicated mortgage finance bank to support both property developers and homebuyers.
“Property developers should be able to access financing from mortgage banks, while homebuyers should also have access to long-term mortgage facilities that allow them to purchase completed houses,” he said.
Under the proposed financing model, developers would access loans to construct residential properties, while prospective homeowners would secure mortgages from financial institutions to purchase completed houses. This would allow developers to recover their investments more quickly and channel resources into additional projects, while buyers benefit from structured, long-term repayment arrangements.
Beyond addressing the housing deficit, improved access to financing could stimulate activity across Zimbabwe’s wider economy, given the construction sector’s links with manufacturing, building materials, transport, engineering and employment creation.
Increased investment in residential construction would create opportunities for local suppliers, contractors, artisans and other players across the built environment, while supporting the growth of related industries.
Manzungu said construction and real estate were becoming increasingly important contributors to economic activity, projecting that the two sectors could account for between 12 and 15 percent of gross domestic product in the coming years.
He made the remarks at a time when Zimbabwe is seeking to expand investment in housing infrastructure and strengthen partnerships between Government and the private sector.
The summit brought together stakeholders from across the construction and property investment industries to explore opportunities for collaboration involving developers, financial institutions, estate agents and suppliers of building materials.
Manzungu also highlighted the potential of public-private partnerships in accelerating housing delivery, with Government providing land while private-sector players contribute financing, labour, equipment and machinery.
Such partnerships could help mobilise additional resources for housing development, accelerate project implementation and expand access to decent accommodation.
He said Zimbabwe could also draw lessons from mortgage financing models operating in other African countries, including Nigeria, as it explores mechanisms to deepen housing finance and broaden access to homeownership.
A functional mortgage financing system would therefore have benefits extending beyond the property market, potentially allowing more Zimbabweans, particularly young professionals and first-time buyers, to acquire homes while stimulating construction investment, employment and economic growth.
By strengthening collaboration between Government, developers and financial institutions, Zimbabwe has an opportunity to build a more sustainable housing finance ecosystem that supports increased housing supply, affordable homeownership and the country’s broader Vision 2030 development ambitions.